The Game of Acceleration

download

What helps startups succeed? One of a few factors identified so far is providing startups with mentoring. According to the U.S. Small Business Administration–and a 2014 similar study in the U.K.–small businesses receiving mentoring services survive longer than non-mentored enterprises.

This fact points to a potential importance of startup accelerators and incubators. Yet, the real value of startup accelerators, which is a relatively new phenomenon, is far from being properly understood. That’s why one can’t but welcome a recent study on the topic conducted by Ian Hathaway who presented his findings in a Brookings Institution Brief and a Harvard Business Review article.

First of all, Hathaway does a great job by precisely defining the very term “startup accelerator” and then explaining why this type of startup support must not be confused with others, primarily with startup incubators and angel investors. Hathaway also provides useful data on the regional distribution of startup accelerators in the U.S.

However, quite naturally, I was mostly interested to know whether or not startup accelerators accelerate startups. Well, it turns out that some of them do and some of them don’t. Published data show that top accelerator programs do shorten the time for their graduates to reach key milestones, such as gaining customer traction, raising venture capital and exiting by acquisition. However, these positive effects dissipate when looking at a broader sample of accelerators. In fact, many programs do not accelerate startup development, and in some cases may be even harmful.

It appears to me that the data collected by Hathaway call for the creation of a national catalog–the U.S. News & World Report of Best Colleges Rankings immediately comes to mind here–providing all existing startup accelerators with a ranking reflecting their effects on the future trajectory of their graduates. Using such a catalog will help startups make informed decisions when considering joining an accelerator program–exactly as the college ranking helps high-school graduates find a school of their dream. Sure, not every startup will be able to enter an accelerator of their choice. But at the very least, they’ll be prevented from spending time and equity on the programs that can’t really accelerate them.

Image credit: http://www.dailygalaxy.com
Posted in Startups | Tagged , , , , , , , , , , , | 1 Comment

Don’t Fire Me: I’m Innovating

Damocles-WestallPC20080120-8842A

It is election season here in the United States, and the stump speech–a standard, boring and short on substance pitch delivered by the acting and aspiring (and often uninspiring) politicians–is back in vogue. Recently, I recognized what the stump speech reminds me. It reminds me of our endless talks about establishing a culture of innovation. The same stuff: too many words, too little substance.

What really bothers me is that while calling to “nurture a culture of innovation,” “promote risk-taking and experimentation” and “celebrate failure” (why on earth should we celebrate failure?), we ignore practical measures to support more entrepreneurial corporate spirit.

So I decided to compose a list of specific corporate policies that organizations may try in order to establish the culture of innovation. I must admit that at the moment, the list is depressingly short. It actually includes only two entries.

  1. I propose to make stock option grants, as opposed to cash bonuses and other monetary rewards, the principal incentive for engaging employees in innovation projects.

This proposal is based on a 2015 finding that companies offering stock options to non-executive employees were more innovative, and that the positive effect of stock options on innovation was more pronounced with longer-term grants.

  1. I propose to place employees involved in innovation projects on fixed-term employment contracts, as opposed to employment-at-will. Alternatively, the creation of tenure-like job arrangements for people involved in strategic innovation initiatives can be considered.

This proposal is taking cue from a 2001 study showing that labor laws making it more difficult to fire employees increase their participation in corporate innovation activities. The authors of the study argued that the lower threat of termination produced by stronger anti-dismissal laws decreased the “cost of failure” for employees to engage in potentially risky innovation projects.

As it turns out, labor laws may have surprisingly strong effect on innovation. Another study has recently found that companies in 34 U.S. states having the so-called constituency statues produce more high-quality patents than those in 16 states lacking the statues. A constituency statue encourages corporate directors to consider non-shareholder (e.g., employees) interests when making business decisions, therefore forcing them to think of the long-term interests of their companies rather than the short-term profits.

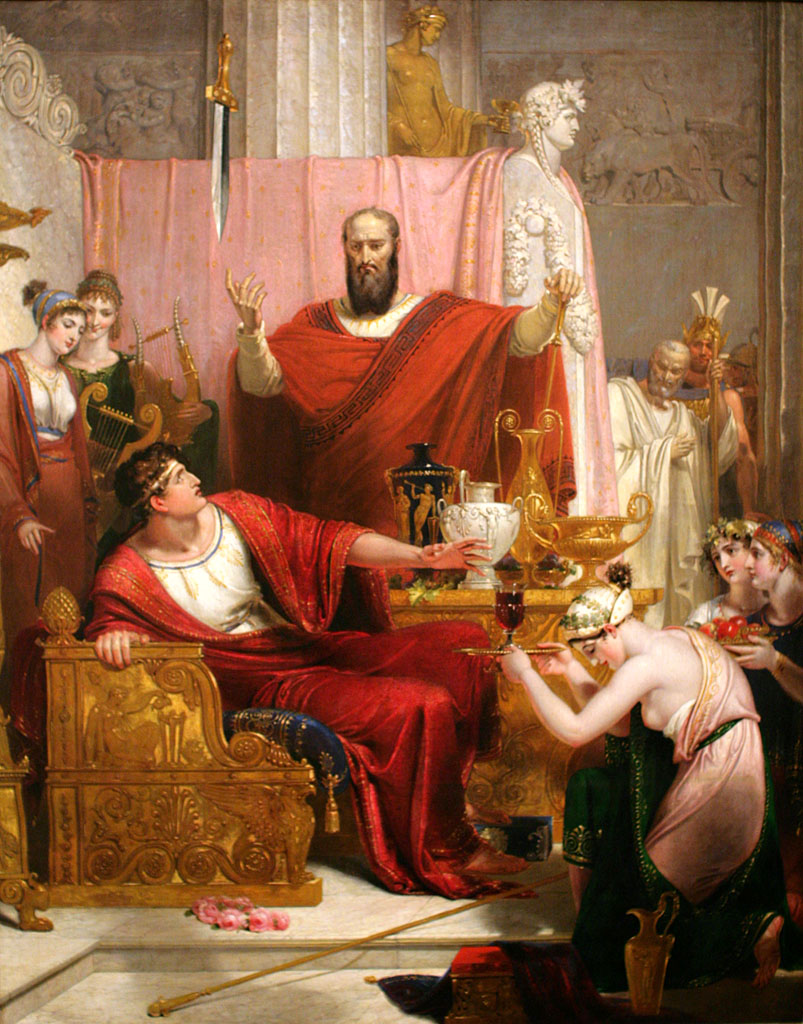
The both studies strongly suggest that the best way to encourage risk-taking and experimentation is to remove the proverbial Sword of Damocles of punishment for innovation failure, something that any organization can easily do by modifying its termination policies. In other words, providing employees with immunity for failed innovation projects is better than celebrating them.

Image credit: Richard Westall, “The Sword of Damocles” (1812)

Posted in Innovation, Rewards and Recognition | Tagged , , , , , , , , , | 17 Comments

Don’t eliminate email. Charge for it.

1l Gerard Terborch (Dutch Baroque Era Painter, 1617-1681) Woman Writing a Letter 1655

In a recent Harvard Business Review piece, Cal Newport proposes to eliminate email. Newport argues that email creates what he calls an “unstructured workflow” that reduces corporate planning and decision making to overcommunication. Newport further asserts that the unstructured flow of emails negatively impacts productivity by preventing employees from working on important tasks. Worse, by being transformed into message-passing robots, highly-skilled knowledge workers are losing satisfaction with their jobs.

Newport wants to replace emails with a system of office hours, in which employees would post a schedule of 2-3 stretches of time during the day when they will be available for communication (in person, by phone or using a messaging app like Slack). The major benefit of the system, in Newport’s view, is that outside their office hours, workers won’t be wasting time answering endless messages and will instead get on doing meaningful things. Needless to say, no one will be bothered to respond to any message at home or on vacation.

I definitely see useful elements in Newport’s proposal, although I’m afraid that creative employees will rapidly find ways to abuse his system of office hours too. But I disagree with Newport on principle: I don’t think that the best way to prevent an excessive use of a commodity (and that’s what email is: a commodity) is to ban it. What is a better way, for example, to prevent tobacco or alcohol abuse: to completely prohibit them or to tax their consumption? I think we all know the answer to this question.

So I propose that instead of eliminating corporate emails, we start charging for them. In practical terms, every business unit in an organization will be paying for each email sent by its worker from its budget, exactly as it would pay for other expenses, such as travel or buying office supplies. Within units, each worker will be assigned a “quota” appropriate to his or her position and responsibility. Alternatively, email usage of each worker will be monitored for signs of “abuse” (exactly as many companies are tracking expenses for the notorious “business meals”).

Admittedly, charging for emails won’t make their flow “structured,” but it will dramatically reduce their volume–and with all due respect to Newport’s disdain for “unstructured workflow,” it is email volume rather than anything else that troubles people. (Not to mention that charging for emails will essentially stop using them for private purposes, something that many companies are concerned about).

I also suspect that paying for email will help many people “hate” it less. After all, don’t we all value things that we chose to pay for?

Image credit: Gerard Terborch “Woman Writing a Letter” (1655) (http://bjws.blogspot.com/2013/01/1600s-women-reading-writing-letters-no.html)

Tagged , , , , , | Leave a comment

Get it right: how to help startups succeed

art-basel-2015-was-body-image-1449832620-size_1000

Given the increasingly important role startups and other small businesses play in today’s economy, supporting them should be considered a policy that will have a profound positive effect on the global economy. From this perspective, pinpointing factors casing startups fail is crucial. Equally, if not more, valuable would be identifying factors that help startups succeed.

A number of such factors have been already identified, and here, I’d like to mention three. First, it’s diversity of the founding team. For example, according to a recent study, startup teams with at least one female founder performed 63 percent better than all male teams. The beauty of this factor is that it’s perfectly actionable: you can easily diversify your founding team by inviting people of different gender, age and prior life experience.

Second, it’s providing startups with advice. According to the U.S. Small Business Administration, small businesses receiving mentoring services survive longer than non-mentored entrepreneurs, the fact that points to a potential value of startup accelerators and incubators. A similar conclusion has been reached in a 2014 study conducted in the UK.

Third, it’s the source of funding. It was demonstrated that the corporate venture capital funding (c-VC) is particularly beneficial to startups: startups that had gone public after being funded by at least one c-VC investor outperformed those funded exclusively by traditional VCs (t-VC), as measured by average annual revenue growth, increase in ROA and stock price performance. The reason might be rooted in the fact that the vast majority of c-VC actively work with their portfolio startups providing them with domain expertise and access to proprietary networks. One could argue that the industry-specific expertise delivered by experienced corporate teams would be much more valuable to startups that the one drawn from the “generalists” employed by t-VCs.

New data add granularity to this picture. Researchers from the Wharton’s Mack Institute for Innovation Management tracked the performance of biotech startups funded by both types of VC and found that startups funded by c-VC demonstrated higher innovation output (in terms of the number of patents granted and scientific articles published) than those funded by t-VCs.

This is not a trivial finding. One can easily expect that large pharmaceutical companies could help biotech startups increase their operational performance by sharing knowledge in clinical trial design, regulatory requirements and compliance. Instead, c-VC funding helped startups display increased innovation rates, which, as I pointed out in my previous post, is crucially important in R&D-intense sectors, such as biotech.

Additional studies will hopefully follow to investigate how c-VC funding specifically benefit startups in other industries.

Image credit: http://www.vice.com/en_au/read/art-basel-2015-was-a-sopping-wet-mess-but-it-was-still-pretty-good

Posted in Startups | Tagged , , , , , , , , , , , , | 2 Comments

Fashion guru Tim Gunn on crowdsourcing

IMG_3335

Tim Gunn is a prominent fashion consultant, TV personality and author. He’s best known as the Emmy Award-winning co-host of the reality show Project Runway; he’s also the author of four bestselling books.

Now, I have to admit that I don’t know what Tim Gunn thinks about crowdsourcing. But just read these lines from his recent book “Tim Gunn: The Natty Professor”:

“Go to a museum! Take every opportunity to discover things you don’t know exist. I encourage rampant googling, too, but when you google, you only find information you search for. When you look around a museum, things find you.”

That’s exactly what crowdsourcing is all about! When you look for a solution to your problem in a traditional way–by reading literature, googling or talking to experts (or “experts”)–you essentially define the borders within which the desired solution can be found. In a sense, you already define this solution in advance.

When you’re crowdsourcing, you don’t have to find solutions. You post your problem on-line, and then solutions find you. Moreover, because of the inherent openness of on-line platforms, these solutions can come from anywhere–even from places “you didn’t know exist”–giving you the diversity of opinions and suggestions you can’t get from any other approach.

Sure, as every tool, crowdsourcing has its application limits. For one, I don’t believe that it will be successful in fashion design; individual creativity shaped by mentoring of bona fide experts like Tim Gunn still matters the most in this business. (Nor do I believe, for that matter, that robots will replace fashion designers any time soon.) But in many other fields of human activity, the ones requiring collective, diverse approaches to complex technical, business or social problems, crowdsourcing is the most effective (and, equally importantly, cost-effective) tool.

Image credit: Tim Gunn signs his book for my wife in Boston (December 2015)

Posted in Crowdsourcing | Tagged , , , , , , , , , , | Leave a comment

When it comes to (some) startups, ideas do matter

o_1a9hmgaas8sk1ltm1h3a1oqhjq47_new

The rate of startup failure remains depressingly high: 55% of startups close before raising $1M in funding, and almost 70% of them die having raised less than $5M. So the question “Why do startups fail?”–or succeed, if you prefer a positive spin–is far from being purely academic, given the important role small businesses play in the global economy.

The lack of market demand, insufficient funding and incompetent team are routinely mentioned to account for the death of yet another startup project. One the other hand, factors making startups more successful have begun to emerge too. For example, the U.S. Small Business Administration reports that small businesses receiving mentoring services survive longer than non-mentored entrepreneurs, the fact pointing to potential value of startup accelerators and incubators. It was also noticed that startups that were funded by at least one corporate VC investor outperformed those funded exclusively by traditional VCs (here and here).

And then, there is a perennially debated question of the importance of the original idea behind any startup. One can often hear that ideas “are a dime a dozen” and that “startups are all about execution;” but a recent study paints more nuanced picture. The authors of the study took a look at a unique entrepreneurial program, the Massachusetts Institute of Technology’s Venture Mentoring Service (VMS). A peculiar feature of this program is that when an entrepreneur joins the VMS, a select group of advisors reviews a summary of the proposed venture, a document that describes technology, business model, key customers, etc., but provides little information about the founding team. Based on this summary, which is essentially just a “naked” idea behind the venture, VMS advisors decide whether to work with it.

Having analyzed the eventual outcomes of 652 ventures gone through VMS in 2005-2012, the authors of the study showed a positive correlation between the number of advisors who wanted to mentor a given venture–a signal of the quality of the original idea–and the likelihood that the startup would eventually reach the commercialization phase.

But there was a twist. The correlation between the advisor interest and startup success was especially strong for ventures with documented intellectual capital in R&D-intense sectors, such as life sciences and medical devices. No such a correlation was seen for non-R&D-intense sectors, such as consumer web and enterprise software.

The significance of the study is in pointing out that in different industries, there are different factors defining the ultimate success of newly emerging companies. These factors need to be further identified, industry by industry (a nice example of an “industry-specific” mentorship can be found here), and used as a tool by everyone working with startups: government agencies, accelerators/incubators and individual mentors.

Image credit: http://kaboompics.com/one_foto/1315

Posted in Startups | Tagged , , , , , , , , , , | 2 Comments

Big Brother Loves You

1975eb72f8571052d313cfe67c1b745b

By contributing to economic growth and creating jobs, small businesses play an important, perhaps, increasingly important, role in the global economy. Moreover, as the cradle for novel technologies and business models, small companies serve as the engine of the innovation process.

Yet, establishing a small business carries a heavy load of uncertainty: only half of new companies survive through their first five years; the attrition rate for high-tech startups exploring new, riskier technologies is even higher. Every measure that could help small companies succeed will therefore have a profound positive effect on the world’s economy in general.

Obviously, governments should take a lead in supporting small businesses; however, big corporations too can assume some responsibility in looking after their little brothers. Getting access to corporate resources, through establishing “big-small” collaborations, will allow small companies rapidly scale their businesses and acquire new customers, increasing their chances to succeed. This brotherly love doesn’t have to be completely altruistic, though. For large companies, working with nimble, inherently entrepreneurial startups can help rejuvenate and speed up corporate innovation programs.

The collaboration between large and small companies may take different forms, and one in particular, corporate venture capital funds (CVC), is rapidly gaining traction. According to a research firm CB Insight, in 2014, there was a 28% growth over 2013 in corporate VC groups making their first investment in startups; the number of existing CVC funds was expected to double in 2015. In fact, one-fifth of all venture deals in Q3 2015 included CVC participation.

Moreover, from the startups point of view, corporate money has turned out to be a particularly successful investment. As described in-depth in a 2013 Harvard Business Review article, over the period of 1980-2004, startups that had gone public after being funded by at least one corporate VC investor outperformed those funded exclusively by traditional VCs (as measured by average annual revenue growth, increase in ROA and stock price performance).

Why is that? The explanation seems to lie in the objectives that the corporate and traditional VCs pursue when investing in startups. While traditional VCs invest capital with the sole objective of financial returns, CVCs often invest for primarily strategic reasons, with financial return being only a secondary consideration. In fact, in a CB Insight survey, 4 out of 5 CVCs named strategic value of working with startups as a key decision driver. Moreover, the vast majority of CVCs actively work with their portfolio companies providing them with domain expertise and access to their proprietary networks. One could argue that the industry-specific expertise delivered by corporate teams would be much more valuable to startups that the one drawn from the “generalists” employed by traditional VCs.

Image credit: Ralph Earle (1751-1801), “Portrait of Two Brothers”

Posted in Startups | Tagged , , , , , , , , , , , , | Leave a comment

The dawn of the “craft economy”?

38617_9741_002

In a 2012 Harvard Business Review article, Maxwell Wessel made an interesting point. He argued that the corporate scale had ceased providing large companies with the same competitive advantage as it used to in the past. Being bigger doesn’t guarantee safe harbor anymore. The cost of starting a new company is becoming lower and lower, and, with first-class management systems available in the cloud and Alibaba.com-driven manufacturing in China, the minimal efficient scale is rapidly shrinking. Small companies can now compete with larger players–and even “disrupt” them–with the ferocity not imagined just a few decades ago.

Writing for HBR in October 2015, Nicco Mele builds up on this argument by pointing out that while the global M&A pace is accelerating, resulting in the creation of new corporate mega-behemoths, America’s largest companies are steadily losing market share. Mele suggests that the ongoing industry consolidation is just a desperate attempt by large corporations to defend themselves from the attacks of smaller competitors. And yet, insists Mele, America’s return to a more entrepreneurial, more fragmented economy–comprised primarily of small, dynamic firms–is inevitable. Mele calls this emerging economy craft economy.

To me, the most intriguing aspect of this discussion is not the predicted demise of the “big,” but, rather, the increasing significance of the “small.” Of course, the important role played by small businesses in the U.S. economy is nothing new. According to published data (here and here), over 50% of American workers (120-130 million) work in small businesses. Small businesses employ half of all private-sector workers and 39% of workers in high-tech jobs. They provide 60% to 80% of the net new jobs annually and they produce 13-14 times more patents per employee than large firms.

At the same time, small businesses don’t reward their employees with a lot of job security: only half of new companies survive through their first five years, and only a third will be in business for at least 10 years. The attrition rate for high-tech startups exploring new, riskier technologies and business models seems to be even higher. It would therefore appear that increasing the longevity of small businesses and improving their wellbeing may have a profound positive effect on the U.S. economy in general.

Ironically, it’s large corporations that can make startups and early-stage companies more successful. This point was highlighted in a recent report by the World Economic Forum (“Collaborative Innovation Transforming Business, Driving Growth”). The report promotes innovation-focused collaboration between young, dynamic firms and large established companies. For small firms, such collaboration allows them to use resources of large companies to rapidly scale their businesses and get access to new markets, increasing therefore their chances for ultimate success. For large companies, working with nimble, inherently entrepreneurial startups may help them succeed with high-risk/high-return innovation projects.

Regardless of whether one believes in Nicco Mele’s concept of craft economy of tomorrow, the real question of today is how small and large companies can work together to ensure global economic growth through innovation. In other words, how David and Goliath should structure their collaboration to craft value together.

Image credit: https://apaintinginthelouvre.wordpress.com/tag/the-battle-of-david-and-goliath/

Posted in Global Innovation, Innovation, Startups | Tagged , , , , , , , , , , , , , , , , , , , | 3 Comments

Investing in culture of innovation

coffee-apple-iphone-desk-large

Everyone would agree that the rational risk-taking–and acceptance of failure as a likely outcome of any exploratory project–represents one of the most crucial components of the bona fide culture of innovation. What is missing in our endless talks about establishing the culture of innovation is which practical steps organizations should take to promote and encourage entrepreneurial spirit of their employees. A couple of studies (nicely summarized in a Harvard Business Review article) shift this conversation from pure talk to specific actions.

The first study (published in the Journal of Financial Economics in January 2015) showed that companies that offered stock options to non-executive employees were more innovative. The positive effect of stock option grants on innovation was more pronounced when the average expiration period of options was longer. It was also demonstrated that the employees involved in innovation activities treated stock options as an incentive to risk-taking rather than an award for superior performance.

Another study (dating back to April 2011) found that certain labor laws that make it more difficult for firms to fire employees increased the engagement of the employees in innovation activities. The authors of the study called this phenomenon the “insurance effect” and argued that the lower threat of termination produced by stronger anti-dismissal laws decreased the “cost of failure” for employees to engage in potentially risky projects. As a result, these employees were more willing to take on innovation projects relative to their engagement in routine projects.

Uniting the both studies is an idea that long-term incentives may have a strong positive effect on innovation. As the HBR article puts it:

“If workers feel pressure to deliver results in the short-term, either for fear of being fired or in order to be promoted, they may be less likely to pursue riskier innovations. On the other hand, if failure in the short-term is acceptable or even rewarded, and if workers have a stake in the company’s long-term performance, they should be more likely to innovate.”

The beauty of the above findings is that they’re easily testable. To do so, companies can introduce these purely administrative policies:

  1. To make stock option grants the principal incentive for engagement in innovation projects (as opposed to cash bonuses and the plethora of non-monetary recognitions and rewards).
  2. To place employees involved in innovation projects on fixed-term employments contracts (as opposed to employment-at-will). Creating tenure-like job arrangements for people involved in strategic innovation initiatives could be another option.

In more general terms, a message that all organizations should hear is that treating employees well will make these organizations more innovative. It’s this simple.

Image credit: www.pexels.com

Posted in Innovation, Rewards and Recognition | Tagged , , , , , | 9 Comments

The beauty of crowdsourcing

22953578025_478c207103_o

Last week, I spoke with Paul Arnold, a seasoned business writer and BBC alumnus. The topic of our conversation was crowdsourcing: how companies use it and why they’re often disappointed with the results of their crowdsourcing campaigns. The full text of the interview can be found here; a few (edited) excerpts follow.

  1. (Why do your clients turn to open innovation?)

There are a few reasons why companies go for open innovation. Firstly, they realize they don’t have internal expertise or experience. That’s the most obvious consideration. The second consideration is that some companies, especially those with some exposure to open innovation through crowdsourcing, realize that there is a diversity of solutions. Sure, they can go to their experts, but not only is it actually more expensive to pay for experts, but there is a limited amount of experts you can talk to, and they are almost always aligned with you. So basically you are asking them what you already know.

The beauty of crowdsourcing is that you are completely agnostic to a solution that may come. It could be completely unexpected. I know cases where companies hired consultants to analyze solutions they were getting through crowdsourcing. They were smart enough to realize that they were onto something very valuable, but the ideas were so novel to them that they couldn’t understand them. And there was no other way to get these solutions except through crowdsourcing. The companies would never have gone to this source, because they didn’t know this source existed.

  1. (Why is crowdsourcing still the least used open innovation tool despite the fact that it’s actually very good?)

Crowdsourcing is damn simple, because it only has two components to it. It is a question and a crowd, and that’s it. The major problem, in my experience, is with the question. Unfortunately, not every problem can be put to crowdsourcing and even if you have the right problem you need to formulate it in such a way that it becomes solvable by crowdsourcing. And many organizations do a very bad job of that. Very often, they try to solve a problem in one giant leap. But experience shows that you have to split your problem into chunks and solve them separately or in parallel. Not only is this more efficient, but it’s actually faster, because when you fail (to solve a problem in one giant leap) you have to start again.

  1. (In your“Are We Faking Innovation?” article you highlighted a surprising survey on innovation where 85% of respondents said that innovation is important to their companies, but 72% had no understanding of what innovation meant to them. Is this something you have come across often?)

Amazingly, it happens all the time. I had a client and spoke with two of their research directors who were working for the same department. When I asked them to give me a definition of what innovation meant for them–in terms of market share, expected revenues, time horizons and things like that–they gave me vastly different responses. And those two were people who had a budget to fund innovation projects under them.

Now, I’m a great fan of diversity, but in some cases, diversity of opinions is not welcome. In fact, it’s not diversity; it’s a lack of an overall corporate oversight. At one point I advocated that companies should write an Innovation Charter, and some people said: well it’s just a piece of paper and everyone is sick and tired of these “mission statements.” Sure, I understand this complaint, but my point is that in very many companies, there is no common language of innovation. So it’s not surprising that people don’t know what innovation means for their particular company.

Image credit: http://fancycrave.com/


Posted in Crowdsourcing | Tagged , , , , , , , , , , , , , | Leave a comment